admin
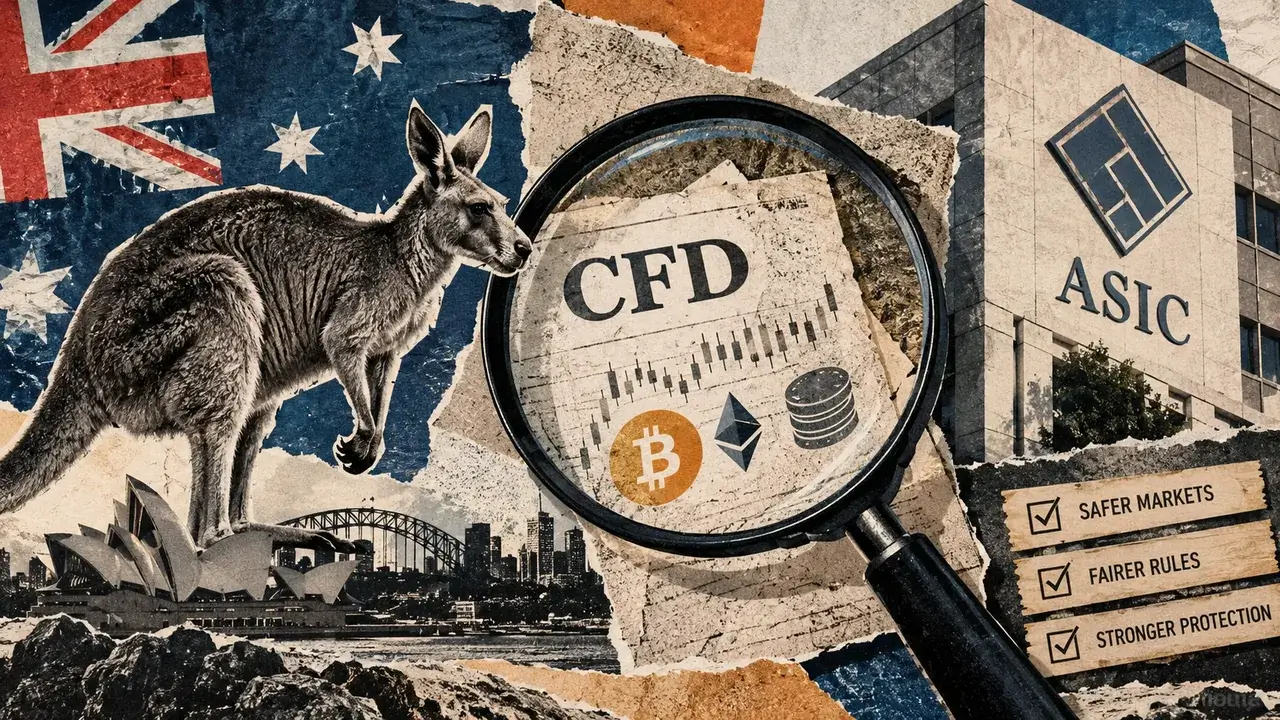
Australia’s primary financial markets regulator, the Australian Securities and Investments Commission (ASIC), has put forward a significant proposal to extend and strengthen consumer protections for retail investors engaging with leveraged financial products, particularly those settled through digital assets. This move, announced on October 12, 2023, aims to close a burgeoning regulatory loophole that has allowed certain high-risk derivatives, economically similar to already restricted contracts-for-difference (CFDs), to operate with less stringent oversight. The proposal comes at a time when retail investors are experiencing substantial financial setbacks, underscoring ASIC’s commitment to safeguarding vulnerable market participants.
The proposed extension of ASIC’s product intervention order, which currently governs CFDs, would encompass qualifying derivatives that are settled via digital assets. This strategic adjustment seeks to ensure that the regulatory framework keeps pace with evolving financial product innovation and investor behaviour. Currently, ASIC’s rules primarily cover CFDs settled in cash or through the netting of obligations between parties. However, a segment of the market has emerged where derivatives with comparable risk profiles are settled by transferring digital assets, thereby sidestepping existing leverage limitations and other consumer protections.
This regulatory initiative is directly informed by ASIC’s findings regarding the significant financial toll on retail investors. Data from the 2023-24 financial year reveals a stark reality: 68% of retail CFD clients incurred losses, collectively amounting to over A$458 million (approximately $325 million). This figure is particularly alarming as it includes A$73 million attributed to fees alone, highlighting the cost of trading even for those who do not ultimately lose their principal investment. While these figures encompass CFD trading across various asset classes, the inclusion of crypto-settled derivatives in the proposed expanded rules suggests a growing concern about the risks associated with these products.
Beyond extending the scope of current protections, ASIC is also seeking to prolong the life of these investor safeguards. The regulator has announced its intention to extend the existing product intervention order for an additional decade, pushing its expiry from March 2027 to 2037, contingent upon government approval. This long-term perspective signals ASIC’s belief that the risks inherent in leveraged retail trading necessitate sustained regulatory vigilance.
Addressing the Crypto Derivatives Gap and Margin Practices
At the heart of ASIC’s proposal is the desire to eliminate the distinction between cash-settled and crypto-settled derivatives. Under the existing framework, CFDs are subject to specific restrictions designed to mitigate the risks associated with high leverage. These include limitations on the maximum leverage offered to retail clients, standardized margin close-out arrangements, negative balance protections, and restrictions on promotional incentives.
The current loophole arises because some derivatives with characteristics akin to CFDs can be settled through the transfer of digital assets, effectively placing them outside the purview of the current product intervention order. ASIC’s proposed amendment seeks to broaden the definition of qualifying derivatives to include those settled via digital assets, irrespective of whether their underlying exposure is tied to cryptocurrencies, traditional assets, interest rates, or market indices.
If implemented, this change would compel brokers and derivatives platforms dealing in these crypto-settled products to adhere to the same stringent regulations that already apply to their cash-settled counterparts. This would mean complying with existing leverage restrictions, which for crypto-related CFDs, currently stand at a maximum of 2:1. This leverage limit necessitates that investors provide at least half of the value of their positions as initial margin, significantly reducing the potential for amplified losses from small market movements. For other asset classes, leverage limits vary, ranging from 5:1 for shares to 30:1 for major currency pairs. The proposed expansion would therefore apply leverage limits based on the derivative’s underlying exposure and contractual structure, rather than a blanket application of the cryptocurrency leverage cap to every digital asset-settled product. It is important to note that certain products, such as some fixed-expiry crypto futures and options, would likely remain outside the scope of these specific retail restrictions.
Historical Context and Impact of Existing Protections
ASIC Commissioner Alan Kirkland has emphasized the tangible benefits of the existing protections, stating that they have "materially reduced investor harm, particularly by limiting excessive leverage." The effectiveness of these measures can be observed in the period following their implementation in March 2021. During the first six months after the protections took effect, aggregate quarterly retail losses in CFD trading saw a dramatic decline of 91%, plummeting from A$372 million to A$33 million. Furthermore, the regulator recorded an 87% reduction in quarterly margin close-outs, a key indicator of reduced speculative trading and forced liquidations. Despite this significant improvement, subsequent reviews have indicated that a majority of retail CFD investors continue to experience losses, underscoring the inherent risks of leveraged trading.
The regulator’s current proposal also aims to tighten practices around how brokers calculate initial margin. A sector-wide investigation by ASIC uncovered instances where firms were offsetting customers’ opposing trading positions. This practice effectively reduced the collateral requirements for clients, potentially exposing them to greater risk without adequate margin coverage. The proposed clarification would mandate that brokers calculate the minimum margin separately for each individual CFD. This change would prevent firms from using one client’s position to offset the margin requirements of another, thereby ensuring that each position is adequately collateralized. ASIC’s prior intervention on margin-netting practices in this sector has already yielded positive results, with 28 issuers refunding over A$36 million to affected retail customers.
Addressing Severe Losses in Options-Linked CFDs
A particular area of concern for ASIC has been CFDs linked to options, where retail investor losses have been exceptionally severe. Data for the 2023-24 financial year shows that a staggering 85% of retail clients trading these products incurred losses. This alarming statistic has prompted ASIC to propose clarifications to margin requirements and to consider whether certain highly speculative options-linked CFDs should remain accessible to retail investors.
The regulator is actively seeking evidence regarding contracts that could potentially expose traders to losses exceeding the initial premium paid for an option. This includes examining contract structures that might present a theoretically unlimited downside exposure for the retail investor. ASIC has not yet made a definitive decision on whether these products should face further restrictions or an outright prohibition, indicating a process of careful deliberation and stakeholder consultation.
Enhanced Scrutiny on Promotions and Educational Tools
In addition to leverage and margin practices, ASIC’s proposed amendments also target promotional activities and the use of educational and research tools by brokers. The regulator aims to impose tighter conditions on promotional discounts, requiring that any permitted offers be made available on substantially equal terms to all retail customers. Furthermore, these offers must be prominently displayed on brokers’ websites and trading platforms to ensure transparency.
To bolster accountability, firms would be required to retain records of qualifying discounts for a period of seven years after the offers have concluded. The proposal also seeks to ensure that educational and research tools are not weaponized to encourage prohibited or excessively risky trading activity. This addresses concerns that sophisticated marketing techniques could inadvertently lure less experienced investors into high-risk financial products.
The Path Forward: Consultation and Regulatory Certainty
The existing CFD intervention order is slated to expire on May 23, 2027. ASIC’s argument for a further 10-year extension is rooted in providing greater regulatory certainty for market participants while simultaneously preserving its ability to adjust or revoke these restrictions should market conditions or risk profiles change. This balanced approach aims to foster a stable operating environment for financial service providers while maintaining the agility to respond to emerging threats to investor protection.
However, these proposed amendments are currently undergoing a consultation process. ASIC is actively seeking submissions from a broad range of stakeholders, including brokers, trading platforms, and consumer advocacy groups. The deadline for these submissions is November 9, 2023. The regulator is particularly interested in understanding which digitally settled products would be affected by the proposed changes, the anticipated compliance costs for firms, and whether any transition period would be necessary for industry players to adapt to the new regulations. The feedback received during this consultation period will be crucial in shaping the final scope and implementation of these significant consumer protection measures. The regulator’s proactive stance reflects a commitment to adapting its oversight to the dynamic landscape of financial markets and to ensuring that retail investors are adequately protected against the inherent risks of leveraged trading, especially in the rapidly evolving digital asset space.