
 James Watt
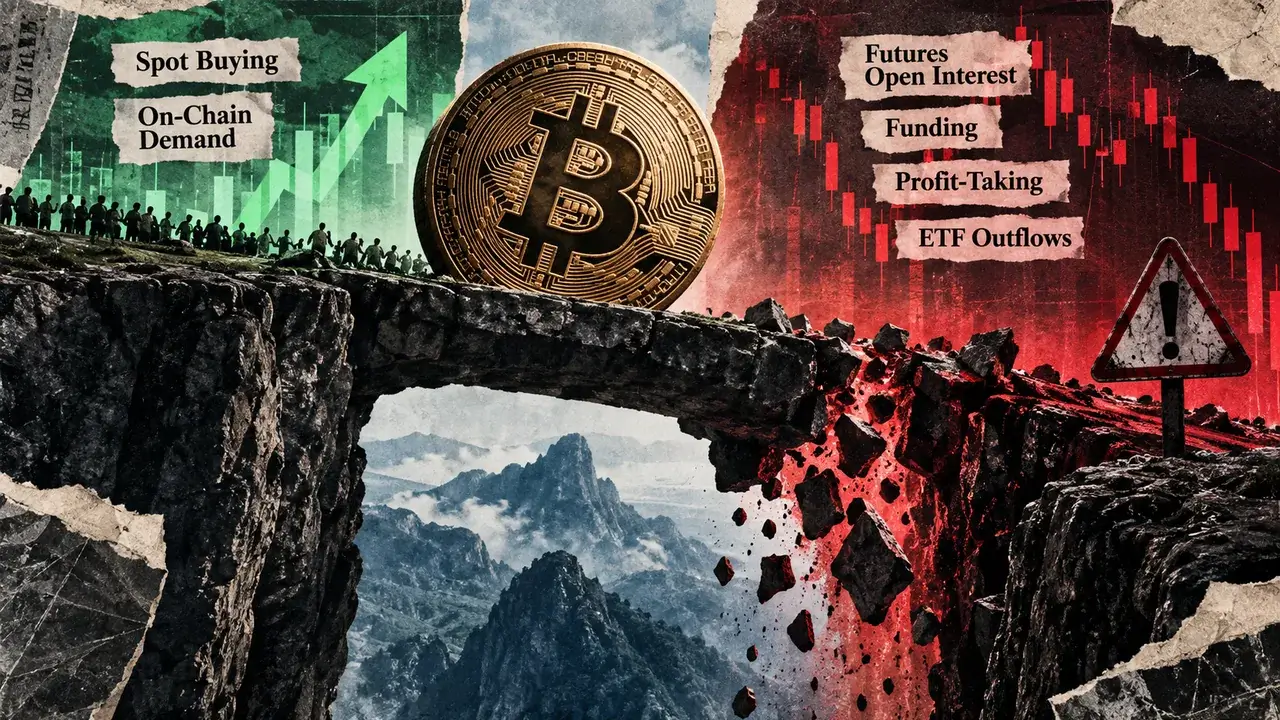
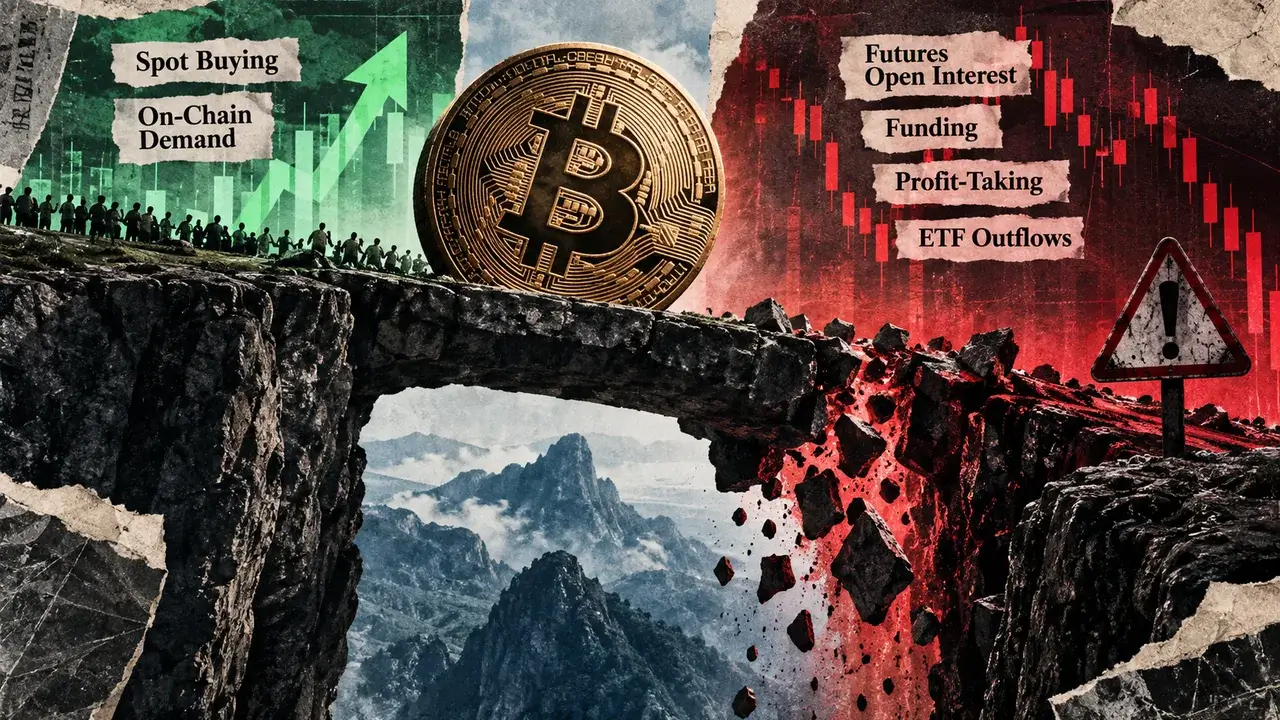
The digital asset market observed a significant shift in capital flow and investor behavior during the third week of September 2026, as Bitcoin recorded an 11.65% weekly rebound that transitioned from a technically driven short squeeze into a period characterized by genuine spot and on-chain participation. Market data from the EU trading session on September 22 placed Bitcoin at approximately $85,877, marking a decisive breach of the $80,000 threshold for the first time in nearly a fortnight. This price action, while initially catalyzed by the forced liquidation of bearish positions, has since shown signs of structural strengthening through increased exchange volume and a resurgence in realized capitalization, suggesting that the rally is finding a more sustainable foundation beyond mere market mechanics.
The latest market snapshot from Glassnode indicates that the asset’s recovery is no longer solely dependent on the "forced buying" associated with short-covering. In the early stages of the advance, Bitcoin’s climb above $85,000 was heavily influenced by the liquidation of over $648 million in short positions, according to data from CoinGlass. When traders who have bet against the price are liquidated, they are forced to buy back the asset to close their positions, creating a feedback loop that accelerates upward price movement. However, for a rally to maintain its integrity, this mechanical momentum must be replaced by "organic" demand—investors who are willing to buy at current prices without being coerced by margin calls.
Evolution of Spot and On-Chain Demand
Evidence of this transition surfaced on September 21, when exchange spot taker flow—a metric that tracks the balance of aggressive market buy orders versus sell orders—flipped from a state of persistent net selling to net buying. This shift was accompanied by a notable increase in trading volume, indicating that market participants were actively pursuing Bitcoin at prevailing market rates. Taker flow is often viewed as a proxy for immediate conviction; while "maker" orders (limit orders) sit on the books waiting for the price to come to them, "taker" orders (market orders) indicate an urgency to enter the market immediately.
The constructive outlook is further supported by on-chain metrics, specifically the monthly change in realized capitalization. Realized cap provides an estimate of the total value stored in the Bitcoin network by valuing each coin at the price it last moved on the blockchain. This serves as a proxy for the network’s aggregate cost basis. By September 21, the monthly change in realized capitalization moved above Glassnode’s high band, suggesting that coins were being repriced at higher levels as they changed hands. This is a critical reversal from the previous week. On September 15, the realized cap had contracted for the first time in nearly a month, ending a 27-day streak of growth. The rapid return to an upward trajectory in realized cap indicates that the network is once again absorbing capital and that the average "buy-in" price for holders is rising.
Chronology of the September Rebound
The path to $85,000 was marked by several distinct phases of market activity:
- September 15: The Contraction Phase. Bitcoin faced a period of stagnation as the realized capitalization contracted. This indicated a momentary pause in capital inflows and suggested that the price, then struggling near $71,300, was at risk of a deeper correction.
- September 16–20: The Consolidation and Build-up. During this window, bearish sentiment increased, leading to an accumulation of short positions as traders anticipated a breakdown. However, the price remained resilient, setting the stage for a squeeze.
- September 21: The Short Squeeze. As Bitcoin broke through key resistance levels, the aforementioned $648 million in short positions were liquidated. This "mechanical" rally pushed the price toward the $85,000 mark.
- September 22: The Spot Transition. During the EU trading hours, the market began to see the "willing buyer" emerge. Spot taker flow turned positive, and the realized cap growth signaled that new investors were stepping in to provide a floor for the price at these elevated levels.
The Risks of Elevated Leverage and Funding
Despite the improvement in demand quality, the market has simultaneously developed new vulnerabilities. Glassnode’s analysis highlights that several derivatives metrics have moved into overextended territory. Futures open interest—the total number of outstanding derivative contracts—is currently sitting above its historical high band. High open interest is a double-edged sword; while it indicates high engagement and liquidity, it also represents a large pool of positions that could be subject to "cascading liquidations" if the price moves sharply in either direction.
Furthermore, futures funding rates have risen above their typical bands. In the perpetual futures market, funding rates are periodic payments made between long and short traders to keep the contract price aligned with the spot price. When funding is high and positive, long traders (those betting on price increases) must pay short traders to maintain their positions. This creates a "carrying cost" for leverage. If the price fails to continue its upward trajectory, these leveraged longs may be forced to close their positions to avoid the mounting costs of the funding fee, potentially triggering a downward correction.
Options positioning adds another layer of complexity. With open interest in Bitcoin options reaching approximately $41 billion, the market is heavily exposed to volatility. Interestingly, the spread between implied volatility (what the options market expects) and realized volatility (what Bitcoin has actually delivered) has moved significantly below its low band. This suggests that options are currently underpricing the actual movement Bitcoin has shown recently. While the "skew"—the difference in demand for puts versus calls—remains within its normal range, it has begun to edge toward puts, indicating that some traders are beginning to hedge against a potential pullback.
Profit-Taking and Institutional Divergence
As Bitcoin hovers near its local highs, the incentive for existing holders to realize gains has increased. Glassnode estimates that approximately two-thirds of the total Bitcoin supply is currently in a state of unrealized profit. Both unrealized gains and actual realized profit-taking have climbed above their respective bands. This suggests that while there is strong demand, there is also a significant "absorption challenge." For the price to continue rising, new spot buyers must be able to absorb the selling pressure from long-term holders who are choosing to lock in profits at $85,000.
An interesting divergence has appeared in the institutional sector. While exchange spot demand is rising, U.S.-listed Bitcoin ETFs showed a weekly net outflow of approximately $300 million as of the September 21 report. This suggests that the current rally is being driven more by direct exchange participants and on-chain activity rather than institutionally mediated fund flows. This disconnect highlights the multifaceted nature of Bitcoin demand; while one cohort (ETF investors) may be de-risking or rebalancing, another cohort (spot market takers) is aggressively accumulating.
Broader Implications and the Volatility Window
The immediate future of Bitcoin’s price action may be influenced by the upcoming options expiry on Deribit, scheduled for September 25 at 08:00 UTC. Major expiry events often act as a magnet for price action as market makers and institutional desks adjust their hedges. While an expiry does not inherently dictate a direction, it frequently serves as a window for increased volatility.
The broader implication for the market is whether the current "spot-driven" phase can outlast the "leverage-driven" risks. If exchange spot taker flow remains in net-buying territory and the realized cap continues to grow, it would suggest that Bitcoin is undergoing a healthy "repricing" event. In this scenario, the market would have the depth to absorb both the profit-taking from old holders and the potential deleveraging of new futures traders.
However, if spot participation begins to fade while futures open interest remains at record highs, the market becomes top-heavy. In such a state, the rebound would be increasingly exposed to the same forced-position dynamics that characterized its opening phase—only this time, the liquidations would likely be on the long side.
Conclusion: A Market at a Crossroads
Bitcoin’s move to $85,877 represents a significant technical and psychological milestone. The transition from a short-covering squeeze to a period of genuine on-chain valuation growth is a constructive signal that suggests the market is finding value at higher price points. The return of positive spot taker flow and the expansion of the network’s cost basis (realized cap) provide a fundamental backing that was absent during the initial burst.
Nevertheless, the presence of "overheated" derivatives indicators—including high funding rates and $41 billion in options exposure—serves as a reminder of the inherent volatility in the digital asset space. The market is currently in a balancing act between organic demand and speculative leverage. The durability of this 11.65% rebound will ultimately be tested by whether the new "willing buyers" can provide enough liquidity to satisfy the "profit-takers" and withstand the inevitable cooling of the futures market. As the September 25 options expiry approaches, the industry will be watching closely to see if Bitcoin can convert its current momentum into a stable new price floor.









