
 James Watt
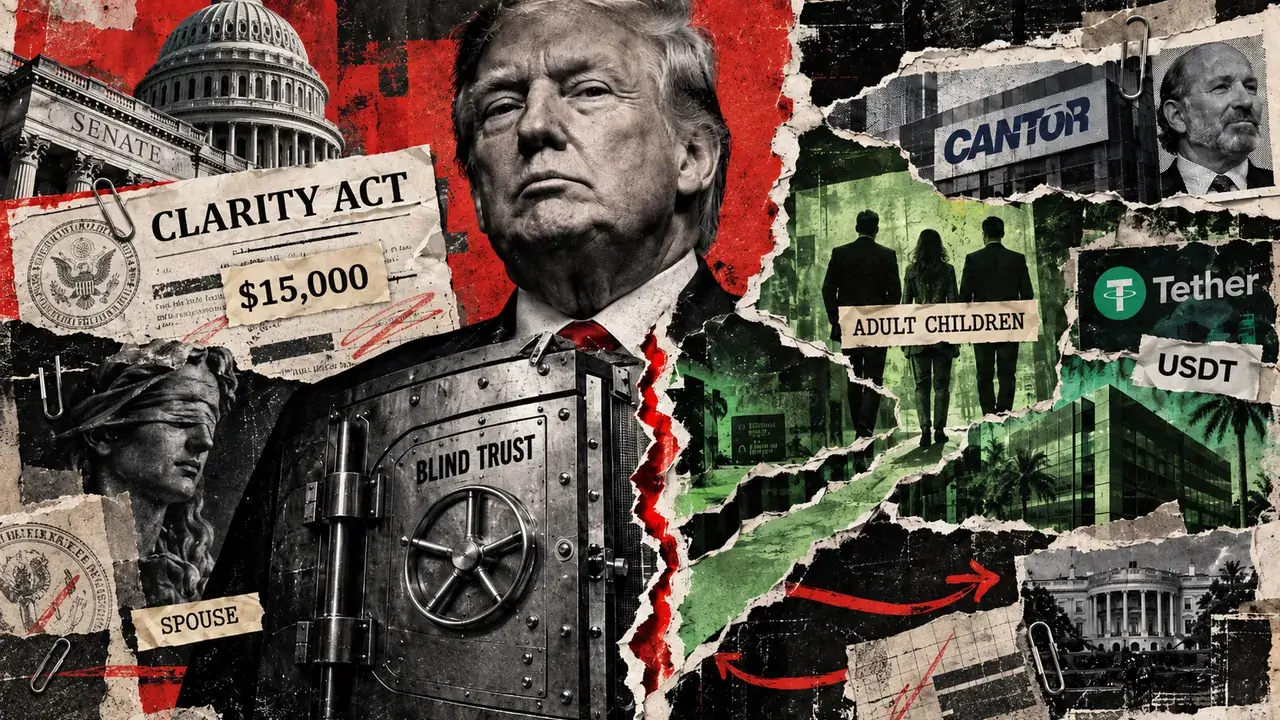
The United States Senate reached a critical juncture this week in the ongoing effort to establish ethical boundaries for federal officials engaged in the burgeoning digital asset market. At the heart of the debate was a specific financial threshold that would have fundamentally altered how high-ranking government employees manage their private interests. Under the final Senate draft of the Creating Legal Accountability for Rogue Innovators and Transparency (CLARITY) Act, any senior federal official holding equity worth at least $15,000 in certain businesses that issue or sponsor digital assets would have been legally compelled to either sell that interest or place it into a qualified blind trust. This restriction was designed to extend to the spouses of these officials, yet it notably excluded their adult children, creating a point of intense political and ethical contention.
The failure of the CLARITY Act to advance on September 15, 2025, means that these specific provisions did not become law. However, the language contained within the draft serves as a revealing blueprint for how Congress views the intersection of private crypto fortunes and public service. While the primary objective of the CLARITY Act was to clarify which federal agencies—specifically the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC)—possess jurisdiction over various crypto market segments, the eleventh-hour negotiations shifted toward the definition of personal and familial financial conflicts. Republicans argued that the final draft was a good-faith effort that incorporated a bipartisan ethics proposal and addressed dozens of Democratic concerns. Conversely, several Democrats maintained that the protections were insufficient, particularly regarding the "adult child" loophole, which they argued allowed for the preservation of family wealth while an official influenced industry-wide policy.
The Case of Howard Lutnick and the Tether Connection
The complexities of these ethical boundaries are perhaps most visible in the professional trajectory of Commerce Secretary Howard Lutnick. Before joining President Donald Trump’s Cabinet in February 2025, Lutnick spent decades at the helm of Cantor Fitzgerald, a cornerstone of Wall Street’s trading and investment infrastructure. Under his leadership, Cantor Fitzgerald became deeply integrated into the cryptocurrency ecosystem through its pivotal relationship with Tether, the issuer of USDT, the world’s most widely used stablecoin with a market capitalization exceeding $120 billion.
Cantor Fitzgerald has served as a primary custodian for Tether’s massive holdings of U.S. Treasury bills, which back the stablecoin’s value. The firm remains a preferred primary dealer for Tether’s regulated U.S. stablecoin operations. This relationship places Lutnick at a unique intersection: as Commerce Secretary, he oversees policies related to international trade and economic security, while the company he built remains the financial backbone for a stablecoin that facilitates global, often offshore, digital asset liquidity.
Upon entering government service, Lutnick adhered to standard ethics protocols by stepping down from his executive roles at Cantor Fitzgerald. In May 2025, the firm announced a plan to transfer his ownership interests into trusts benefiting his adult children. Securities and Exchange Commission (SEC) filings from October 2025 confirmed that the transfer was completed, with his son, Brandon Lutnick, assuming control of the company and the voting interests of the trusts. While this move legally separated the Secretary from beneficial ownership of the securities, it left the Lutnick family’s economic future inextricably tied to the success of Cantor Fitzgerald and its crypto-centric partnerships.
Defining the Scope of the Proposed Ethics Rule
The ethics rule proposed in the CLARITY Act was more nuanced than a blanket ban on cryptocurrency ownership. It did not target the mere holding of Bitcoin or Ethereum by a member of Congress or a Cabinet official, provided those holdings were below the reporting threshold or held as personal investments. Instead, the draft targeted "equity interests" in entities where the primary revenue source—defined as the largest source of income in any of the three preceding calendar years—was the issuance or sponsorship of digital assets.
This definition specifically excluded "tokenized traditional assets," such as real estate or stocks represented on a blockchain, focusing instead on the native crypto industry. Furthermore, the rule would have prohibited officials from receiving compensation for issuing or sponsoring digital assets while in office. The list of covered individuals included:
- The President and Vice President of the United States.
- Senior executive branch officials (Cabinet members and deputies).
- Members of the House of Representatives and the Senate.
- Federal officeholders already subject to public financial-disclosure requirements under the Ethics in Government Act of 1978.
The inclusion of spouses in these restrictions was a standard application of federal conflict-of-interest logic. However, the exclusion of adult children became the primary catalyst for the bill’s defeat. Critics argued that in the modern financial landscape, particularly within the crypto sector, the distinction between an official’s wealth and their adult children’s wealth is often a matter of legal paperwork rather than economic reality.
The Trump Family and the Private Token Economy
The debate over adult children was not merely theoretical; it was directly linked to the financial disclosures of President Donald Trump. Reuters reported that Trump’s 2025 certified financial disclosure showed more than $1.4 billion in income derived from various crypto ventures. A significant portion of this revenue was tied to World Liberty Financial and various "Official Trump" branded digital assets.
World Liberty Financial was launched in collaboration with members of the Trump family, including the President’s sons, Donald Jr. and Eric Trump. While the White House has consistently stated that the President’s finances are managed by his children and that his private interests do not dictate administration policy, the CLARITY Act would have put this claim to a statutory test. Under the proposed rules, if the President held a direct qualifying interest, he would have been forced to divest. However, because the entities are largely managed and owned by his adult children, the proposed ethics rule would likely have left the family’s crypto business intact and under family control, even as the administration shaped the regulatory environment for stablecoins and decentralized finance (DeFi).
Legal Precedents and the Mechanics of Conflict Law
Federal conflict-of-interest law, primarily governed by 18 U.S.C. § 208, generally prohibits an executive branch employee from participating personally and substantially in a government matter that has a direct and predictable effect on their own financial interests or those of their spouse or minor children. Historically, the law has stopped at the "adult child" boundary to avoid penalizing government employees for the independent financial decisions of their grown offspring.
However, crypto assets present a unique challenge to this traditional boundary. Unlike a diversified portfolio of stocks, a private crypto business or a specific token issuance can see its value swing by hundreds of millions of dollars based on a single regulatory clarification or a change in banking access. When an official’s adult child runs a company whose viability depends on the parent’s policy decisions, the "independence" of that child’s financial interest becomes a subject of intense public scrutiny.
The CLARITY Act attempted to address this by mandating the use of "qualified blind trusts." Under the Ethics in Government Act, a qualified blind trust is a rigorous legal instrument. It requires:
- An independent trustee who has no prior relationship with the official.
- Total discretion for the trustee to sell the original assets and reinvest in unknown holdings.
- Strict "blindness," where the official is prohibited from receiving any information about the trust’s specific holdings other than the total value or the amount of income generated.
The proposal in the CLARITY Act was significant because it sought to move beyond simple disclosure. Disclosure only informs the public of a potential conflict; a blind trust or divestment is intended to remove the conflict entirely. By rejecting the bill, the Senate effectively maintained the status quo, where disclosure remains the primary tool for ethical oversight, leaving the substantive economic links between officials and their families’ crypto businesses unregulated by new specific statutes.
Chronology of the CLARITY Act Ethics Debate
The evolution of the CLARITY Act’s ethics provisions followed a rapid timeline throughout 2025, reflecting the urgency of the crypto industry’s growth:
- January 2025: Initial drafts of the CLARITY Act focus almost exclusively on stablecoin reserve requirements and the division of power between the SEC and CFTC.
- February 2025: Howard Lutnick is confirmed as Commerce Secretary. Public interest groups begin raising questions regarding his ties to Tether through Cantor Fitzgerald.
- May 2025: Lutnick announces the transfer of his business interests to his children’s trusts, a move aimed at complying with existing executive branch ethics guidelines.
- July 2025: A bipartisan group of senators introduces the ethics amendment to the CLARITY Act, proposing the $15,000 equity threshold and the blind trust requirement.
- August 2025: President Trump’s financial disclosures reveal $1.4 billion in crypto-related income, intensifying the focus on the "adult child" exception in the proposed bill.
- September 10-14, 2025: Intense negotiations occur behind closed doors. Republicans agree to lower the threshold and include spouses, but refuse to extend the rule to adult children, citing concerns over government overreach into the lives of private citizens.
- September 15, 2025: The Senate fails to achieve the 60-vote threshold required to advance the bill. Democrats cite the "Trump loophole" as a primary reason for withholding support, while Republicans blame Democratic intransigence for sinking a comprehensive regulatory framework.
Broader Impact and Regulatory Implications
The failure of the CLARITY Act leaves the cryptocurrency industry in a state of continued regulatory ambiguity. Without a clear federal statute, the "regulation by enforcement" era is likely to persist, with the SEC and CFTC continuing to battle in court over the classification of various tokens.
From an ethics standpoint, the collapse of the bill highlights an institutional struggle to adapt 20th-century ethics laws to 21st-century digital wealth. In the traditional corporate world, divestment from a public company like General Motors is straightforward. In the crypto world, where wealth is often tied to private token allocations, liquidity pools, and family-run "founder" entities, the process of separating an official from their assets is far more complex.
The debate also underscores a growing concern regarding "regulatory capture" in the digital asset space. When the individuals responsible for writing the rules—or their immediate family members—stand to gain or lose significantly based on those rules, market participants may lose confidence in the fairness of the U.S. financial system. Stablecoin regulation, in particular, is a high-stakes arena; a bill that favors one reserve model over another can effectively pick winners and losers in a trillion-dollar global market.
While the $15,000 threshold of the CLARITY Act is currently a dead letter, the issues it raised will inevitably resurface. As more individuals from the private financial and technology sectors enter public service, the question of where a government official’s fortune ends and their family’s begins will remain one of the most difficult problems for Washington to solve. For now, the legal separation between officials and their adult children remains a firm line in the sand, even as the economic reality of family-held crypto wealth continues to blur it.









