
 admin
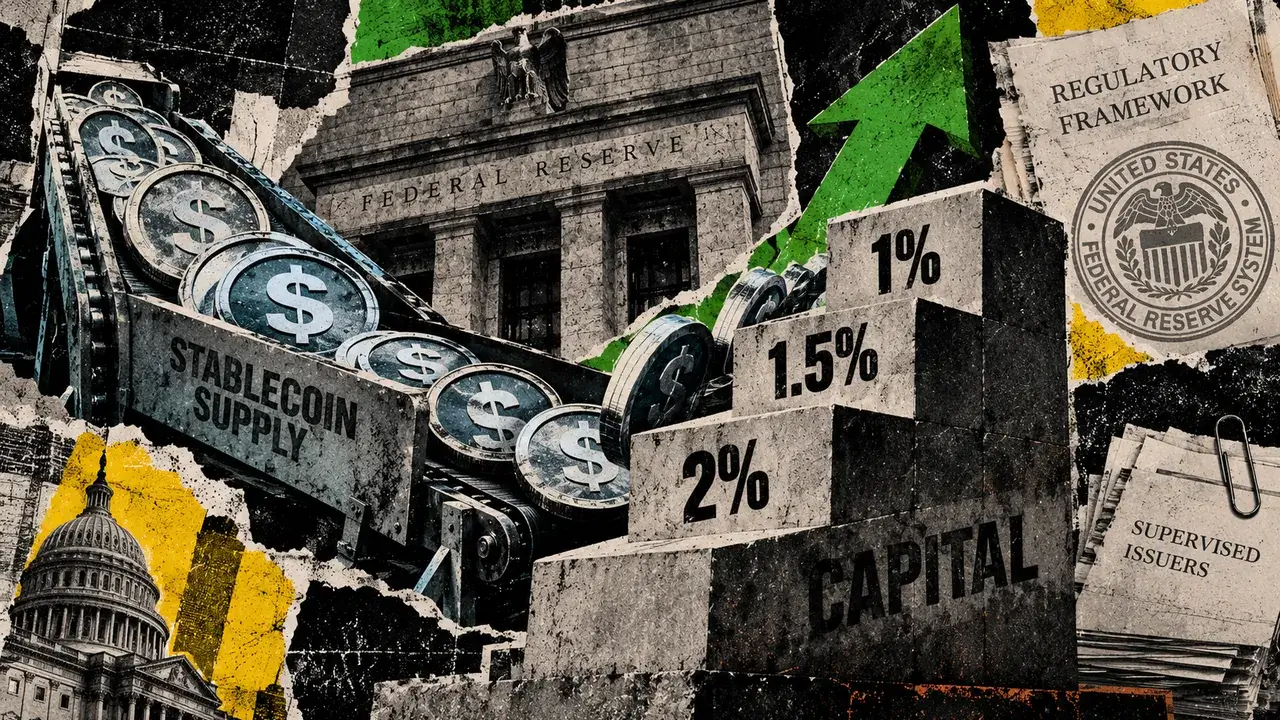
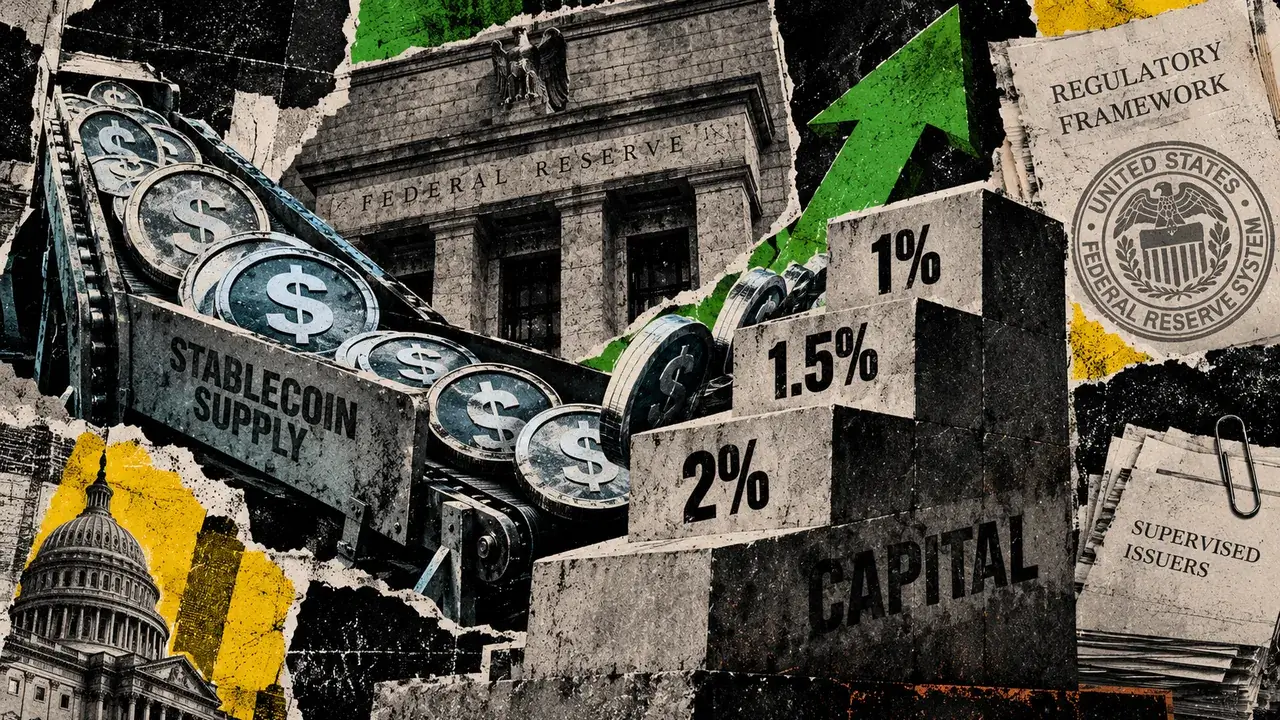
A hypothetical payment stablecoin issuer within the Federal Reserve’s proposed supervisory scope, with $1 billion in circulation and no revenue from activities outside its reserve assets, would start with a $20 million baseline operational-risk capital charge under the Fed’s proposal announced Sept. 24. This figure represents the initial operational-risk capital requirement before any adjustments for loss history or other applicable capital charges. Crucially, this proposed capital charge operates independently of the requirement for issuers to maintain reserves backing their stablecoins. The Federal Reserve’s approach signifies a fundamental shift, directly linking the growth and scale of stablecoin issuance to a tangible capital cost for supervised entities.
The proposal, detailed in a Board memo released alongside a separate proposal for insured state member banks seeking to issue payment stablecoins through subsidiaries, outlines a tiered system for calculating this operational-risk capital. This framework is slated to apply to approved stablecoin-issuing subsidiaries of insured state member banks and certain qualifying state-chartered issuers that transition to Federal Reserve supervision. In contrast, the Office of the Comptroller of the Currency (OCC), under its own pending proposal, has adopted a different methodology. The OCC’s approach focuses on tailoring capital amounts to each issuer’s specific business and risk profile, supplemented by a separate pool of liquid assets earmarked to cover operational expenses.
The Fed’s Tiered Capital Charge Mechanism
The Federal Reserve’s proposed capital framework establishes a direct correlation between the volume of outstanding payment stablecoins and the baseline operational-risk capital requirement. This means that as an issuer’s stablecoin supply expands, so too does its mandated capital reserve, even if the issuer’s revenue streams from activities beyond reserve management remain negligible.
The calculation begins with a baseline operational-risk capital charge based on the total value of payment stablecoins outstanding. For the initial $20 billion in stablecoins in circulation, the Fed proposes a 2% capital charge. This rate then decreases for subsequent tranches: 1.5% for the next $30 billion in issuance, and 1% for any amount exceeding $50 billion. These are marginal rates, meaning that crossing a specific threshold would only affect the capital requirement on the additional issuance beyond that point, not the entire outstanding balance.
To illustrate the potential impact, consider a hypothetical issuer with $10 billion in payment stablecoins outstanding and no non-reserve revenue. Under the Fed’s proposed formula, the issuance portion of the baseline operational-risk capital would amount to $200 million. This entire sum would fall within the first tier, subject to the 2% capital charge.
Furthermore, the Fed’s proposal includes an adjustment for revenue generated from non-reserve assets. The Board’s memo specifies that 25% of the issuer’s three-year average annual revenue from these non-reserve activities would be added to the baseline operational-risk capital calculation. This provision acknowledges that issuers with diversified revenue streams might warrant a different capital treatment, reflecting their broader business operations.
The Role of Loss History and Other Capital Components
Beyond the baseline operational-risk charge tied to issuance volume and non-reserve revenue, the Fed’s proposal also incorporates a loss-history adjustment. This mechanism allows the operational-risk charge to be adjusted upwards or downwards based on the issuer’s realized losses over a defined period. Consequently, an individual issuer’s total capital requirement would be a composite figure, reflecting not only its scale of operations but also its historical performance in managing risks. Other applicable capital charges, not directly detailed in this specific operational-risk framework, could also contribute to the overall capital mandate.
It is crucial to distinguish between capital requirements and stablecoin reserves. The Fed mandates that covered issuers must maintain eligible reserve assets with a fair value at least equal to the par value of their outstanding coins. This ensures that each stablecoin is fully backed by an equivalent value of reserve assets. Separately, the Fed proposes a capital charge of 2% on reserve assets that are classified as uninsured deposit claims or are undercollateralized reverse repurchase agreements. These potential credit-risk charges are distinct from the operational-risk calculation and aim to mitigate risks associated with the nature of the reserve assets themselves. The one-to-one backing of stablecoins by reserve assets remains a fundamental requirement, independent of the proposed baseline capital figures.
The Board memo clarifies that the 2% capital charge on specific reserve assets is primarily applicable to state-qualified issuers that are uninsured state-chartered depository institutions with at least $10 billion in payment stablecoins outstanding and that transition under the proposed GENIUS Act framework. This $10 billion threshold is specifically tied to this particular transition category, indicating a targeted approach for certain large, state-chartered issuers.
The scope of Fed supervision is contingent on the legal status of the issuer and its primary regulator. The $1 billion example cited earlier assumes an issuer that qualifies for Board supervision and does not have any company-specific factors that would alter the standard calculation. This highlights the importance of the legal and regulatory landscape in determining which entities fall under the Fed’s purview and how these capital proposals would be applied.
The Federal Reserve’s announcement on September 24, detailing these proposals, was part of a broader regulatory push. Alongside the operational-risk capital framework, the Board also unveiled a separate proposal outlining the application process for insured state member banks seeking to issue payment stablecoins through subsidiaries. Both of these proposals are currently open for public comment and are subject to revision through the formal rulemaking process, allowing stakeholders to provide feedback and influence the final regulatory outcomes.
The OCC’s Divergent Regulatory Path
In contrast to the Federal Reserve’s issuance-based capital charge, the Office of the Comptroller of the Currency (OCC) has charted a different course with its March proposal. The OCC’s approach emphasizes a capital framework that is intrinsically linked to the specific business model and risk profile of each individual issuer. For newly chartered or licensed issuers, the OCC proposes an initial minimum capital amount that is determined based on a thorough assessment of their business plan and anticipated risks. During an initial "de novo" period, this capital requirement would generally be subject to a floor of $5 million.
Moving beyond the initial phase, the OCC’s proposal requires ongoing capital levels that are commensurate with the issuer’s evolving business model and its specific risk profile. The proposed rule text leaves the precise determination of this ongoing capital amount to a supervisory assessment, allowing for a dynamic and adaptive regulatory approach.
Furthermore, the OCC has introduced a distinct operational backstop requirement. This backstop mandates that issuers maintain readily available liquid assets equivalent to 12 months of their total identified expenses. These operational backstop assets must be segregated and clearly distinct from the assets backing the stablecoins themselves. The purpose of this liquidity requirement is to ensure that issuers have sufficient resources to sustain their operations during periods of disruption or unexpected events. It is a liquidity measure, calculated based on expenses, whereas the Fed’s operational-risk capital charge is primarily based on issuance volume and non-reserve revenue.
While the OCC’s current proposal omits a percentage-based capital charge tied to the volume of coins outstanding, the regulator did explore this possibility as an alternative during the comment period. The OCC specifically sought public feedback on a variable capital component linked to the number of outstanding stablecoins. However, this approach was not included in the proposed rule text, indicating a preference for its expense-based liquidity backstop and risk-tailored capital assessment.
The fundamental difference between the two regulatory approaches lies in their starting points for capital determination. The Fed’s operational-risk capital charge begins with the scale of issuance and non-reserve revenue, while the OCC’s framework leans towards a bespoke assessment of business plans and operational expenses. These differing methodologies apply across distinct supervisory jurisdictions, and the final capital requirements for each regulator remain subject to refinement following the public comment periods.
The OCC’s proposal was officially published in the Federal Register on March 2, and its designated comment period concluded on May 1. For the Federal Reserve’s proposals, the Board has indicated that comments will be accepted for 60 days following their publication in the Federal Register. While the September 24 release did not provide a specific calendar deadline, the ongoing comment periods represent a critical juncture for industry stakeholders to voice their perspectives. The ultimate calibration of the Fed’s loss adjustment mechanism and the finalization of capital and liquidity rules by both regulators, after considering public feedback, will be consequential developments for the stablecoin ecosystem. The divergence in these approaches underscores the evolving nature of stablecoin regulation and the ongoing debate about the most effective means of ensuring stability and mitigating risks within this rapidly developing financial sector.








